Medicare Supplement plans in Ocean City, MD
Steady costs and no network, whether you are in West Ocean City or visiting the grandkids
A Supplement, also called Medigap, pays most of what Original Medicare leaves behind. For retirees who split time between the beach and family elsewhere, that freedom is often the deciding factor.
Talk through your optionsHow a Supplement fits with Original Medicare
Original Medicare (Part A and Part B) pays a large share of hospital and doctor bills, but not all of it. In 2027 you face a $1,776 Part A deductible for each hospital benefit period, a $292 Part B deductible, and 20 percent coinsurance on most outpatient care with no yearly limit.
A Medicare Supplement policy from a private carrier fills those gaps. There is no network, no referral and no prior approval from the plan: if a provider accepts Medicare, your Supplement pays its share. That works the same at TidalHealth Atlantic in Berlin, at a specialist in Baltimore, or at a clinic near your grandchildren in Ohio.
Get Supplement quotesReading the Supplement plan chart
Every Supplement plan with the same letter covers the same benefits, whichever carrier sells it. That makes the chart below the best place to start. Read across a row to see which plans pay a given cost, and down a column to see everything one plan covers. A check means the plan pays 100 percent of that cost; a percentage means it pays that share.
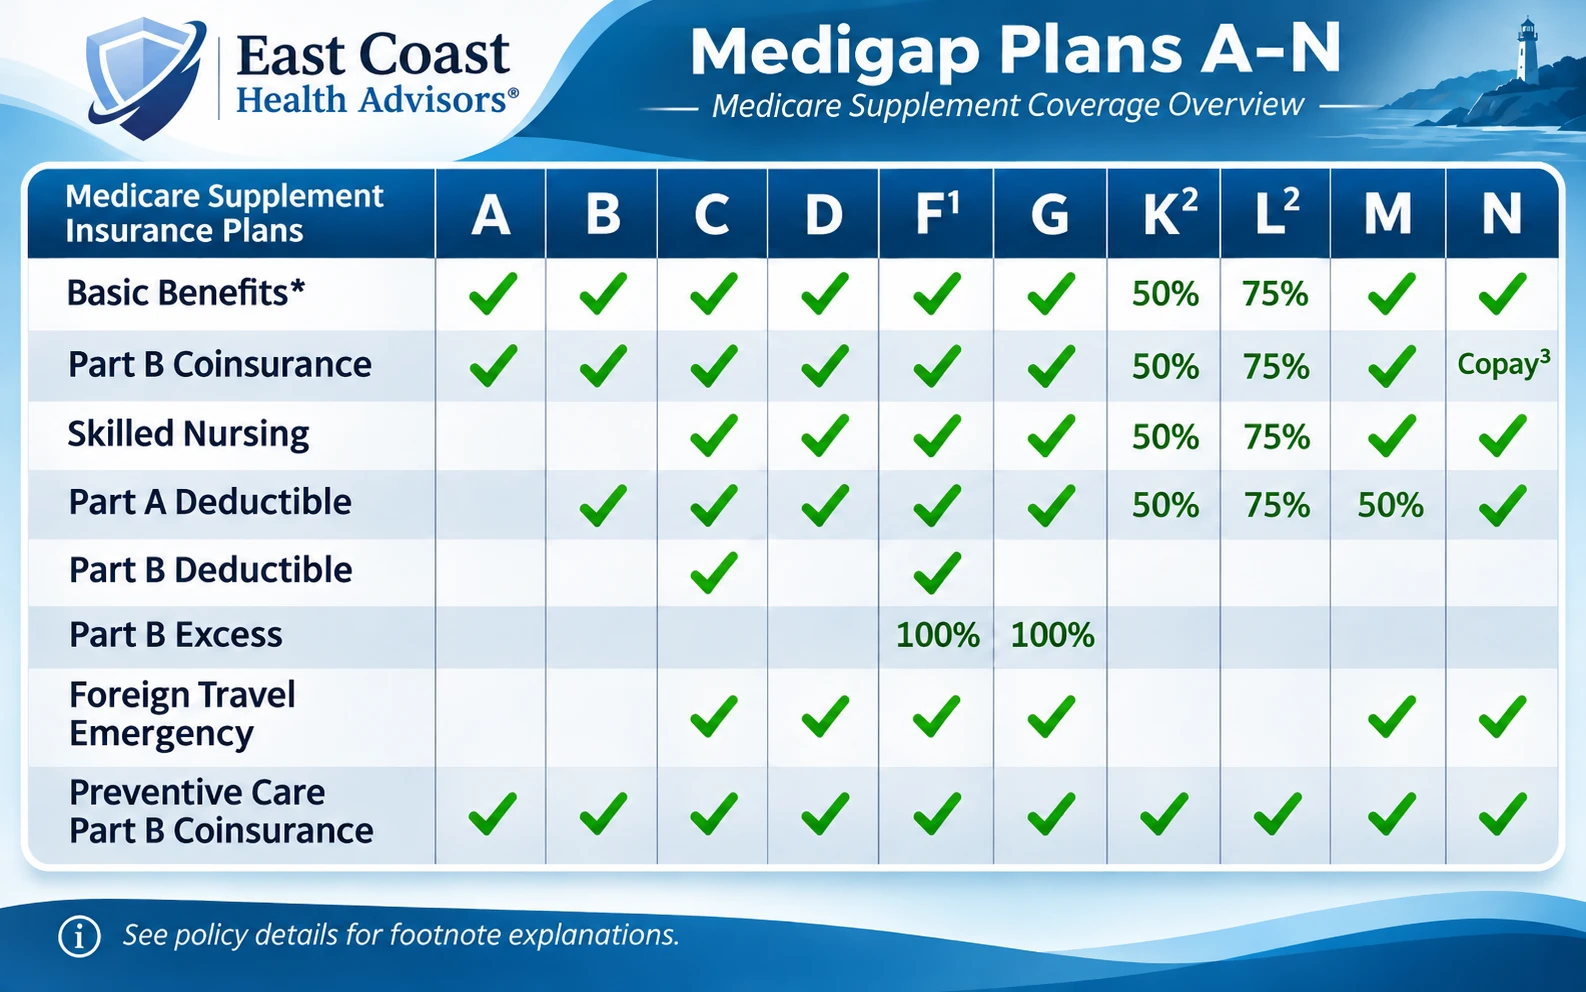
Most new enrollees in Ocean City narrow the field to three plans: Plan G, Plan N and High Deductible Plan G. Here is how they compare.
Plan G
Plan G pays every gap in the chart except the Part B deductible, which is $292 in 2027. After you meet that deductible, Medicare approved care is covered in full for the rest of the year, including Part B excess charges that some doctors bill.
Advantages
- Very little to pay after the Part B deductible
- Covers Part B excess charges
- Foreign travel emergency coverage included
Disadvantages
- Higher monthly premium than Plan N or High Deductible G
- You still pay the Part B deductible yourself
- Does not include prescription drugs
Plan N
Think of Plan N as Plan G with small speed bumps. Hospital stays, skilled nursing and the Part A deductible are handled the same way, but a visit to your doctor in Berlin may carry a copay of up to $20, and a trip to the emergency room that does not lead to an admission can cost up to $50. Any Part B excess charge a provider bills is yours to pay.
Advantages
- Usually a lower premium than Plan G
- Same hospital and skilled nursing coverage as Plan G
- Foreign travel emergency coverage included
Disadvantages
- Small copays at some office and ER visits
- Does not cover Part B excess charges
- You pay the Part B deductible yourself
High Deductible Plan G
High Deductible G works like Plan G after you meet a yearly deductible, which is $3,050 in 2027. Until then you pay Medicare approved costs yourself. It suits healthy retirees who want strong protection against a big year at a lower monthly premium. HDG is Plan G with a $3,050 deductible.
Advantages
- Lowest premium of the three in most cases
- Full Plan G coverage once the deductible is met
- Caps your yearly exposure for Medicare approved care
Disadvantages
- You pay up to $3,050 in Medicare approved costs first
- A busy medical year costs more out of pocket
- Harder to budget month to month
Moved to Ocean City with a Supplement from another state?
Good news first: a Supplement policy is not tied to a service area, so it keeps working after you move to the shore. Your carrier may reprice it for your new Worcester County ZIP code, sometimes up and sometimes down, so it pays to compare once you settle in.
The fine print matters if you want to switch. Maryland gives people with a Supplement a yearly window, covering their birthday and the 30 days that follow, to move to a plan with equal or lesser benefits without answering health questions. That rule is written for policies issued in Maryland. If your policy came from Pennsylvania, Virginia or New Jersey, changing carriers outside a protected window may involve health questions. We will check which rules apply to you before you cancel anything.
If you are leaving a Medicare Advantage plan because you moved out of its service area, you may have a guaranteed right to buy certain Supplement plans with no health questions. That right has a deadline, so call us soon after the move.
When to buy, and how Maryland prices it
The calmest time to buy is your Medigap open enrollment: six months that begin once you are 65 and your Part B has started. In those months a carrier must accept you at its standard rates, whatever your health history.
Carriers in Maryland price Supplements one of three ways. Issue age pricing is based on your age when you buy. Attained age pricing rises as you get older. Community rating charges everyone the same regardless of age. Many carriers also offer a household discount when you and your spouse or partner enroll together. Because prices vary by carrier, age and ZIP code, we quote several carriers side by side, and rates can change without notice.
A Supplement does not include drug coverage, so pair it with a Part D plan. Our Ocean City drug plan guide covers that piece, and our Medicare Advantage guide explains the other path if an all in one plan appeals to you.
Why work with an independent broker
We represent many Supplement carriers, so we can show you how the same Plan G is priced by several companies, and how each one has raised rates over time. You pay the same premium whether you enroll through us or directly, and we are here every year after.
Four steps to a Supplement that fits
- Step 1
Gather the basics
Your Medicare card dates, your ZIP code, your doctors and any health changes since you turned 65.
- Step 2
Compare plans and carriers
We line up Plan G, Plan N and High Deductible G from several carriers, with each carrier's pricing method.
- Step 3
Pick your drug plan
We match a Part D plan to your prescriptions and the pharmacy you actually use.
- Step 4
Enroll and check in yearly
We handle the application with you and review your coverage each fall.
Supplement questions from Ocean City
Does a Medicare Supplement include prescription drug coverage?
No. Supplement plans sold today do not cover outpatient prescriptions, so most people pair one with a separate Part D drug plan. Our drug plan guide explains how to pick one around your pharmacy.
Can I still buy Plan F?
Plan F is reserved for people whose Medicare eligibility began before 2020, and Plan C closed on the same schedule. If you turned 65 in 2020 or later, Plan G is the closest match, and Plan N and the other letters are open to you as well.
Does my Supplement work when I travel?
Inside the United States, a Supplement works with any provider who accepts Medicare. Plans C, D, F, G, M and N also include foreign travel emergency coverage: after a $250 yearly deductible, the plan pays 80 percent of emergency care abroad, up to a $50,000 lifetime limit.
Will my price go up?
Supplement premiums usually change over time. How they change depends on how the carrier rates the policy (issue age, attained age or community rating), on your ZIP code and on the carrier's claims experience. We show you how each carrier rates before you choose.
Prefer to talk it through?
Ten minutes on the phone usually settles it. Tell us which doctors you see, what you take and what you want to spend, and we lay the choices out next to each other.
Free quotes, no obligation
Get Supplement quotes for your Ocean City ZIP code
Tell us your age and ZIP and we will send current Supplement, Advantage and drug plan options for your address. Prefer a conversation? Call us or pick a time that suits you.
(410) 896-1212
support@echa.biz
Book an appointment